A charge shows up on your statement that you do not recognize, or a package never arrives, or what arrived is nothing like what was promised. You are not powerless. Card disputes exist precisely for these moments, and knowing the process turns a stressful month into a paperwork exercise.
This guide explains, in plain terms, how disputes work, what rights stand behind them, and the steps that give a claim its best chance. It is educational and general in nature; exact rules vary by card network and issuer, so always check your own cardholder agreement. For related coverage, see How Online Payment Processing Actually Works Behind the Scenes.
What a Chargeback Actually Is
A chargeback is a return of money to a payer, most often a consumer, after a card transaction is reversed. As Wikipedia's overview explains, the reversal is ordered by the bank that issued your card, typically to settle a card dispute. It differs from a merchant refund: the issuer pulls the funds back, and the merchant must respond.
The mechanism exists mainly for consumer protection. It covers unauthorized transfers, such as those caused by identity theft, and disputes over goods and services. It also has a dark twin, sometimes called friendly fraud, when a buyer who authorized a purchase later tries to reverse it dishonestly. Use the tool for its intended purpose, and it works in your favor. We covered a connected angle in Digital Wallets vs Cards: Which Should You Use Day to Day?.
The Rights Standing Behind Your Claim
In the United States, holders of credit cards get reversal rights from Regulation Z of the Truth in Lending Act, while debit card holders are covered by Regulation E of the Electronic Fund Transfer Act. Similar rights extend in other countries through card networks and local rules.
One law is especially practical to know. Under the Fair Credit Billing Act, passed in 1974, consumers can dispute billing errors on open end credit accounts such as credit cards. The dispute must reach the creditor within sixty days of the statement that first showed the error, and it must go to the address the statement lists for billing inquiries, not the payment address. The issuer must acknowledge the dispute within thirty days and, within ninety days, either correct the account or explain why it believes there was no error.
The law's list of covered errors is broad: charges you did not make, charges in the wrong amount, goods never received, goods not delivered as agreed, calculation errors, and charges you asked to have clarified or proven.
How to File a Dispute, Step by Step
A strong dispute is a documented dispute. These steps keep yours clean.
- Start with the merchant. Many problems are genuine mistakes, and a refund at this stage is the fastest outcome.
- If that fails, contact your issuing bank and file a complaint about the specific charge on your statement.
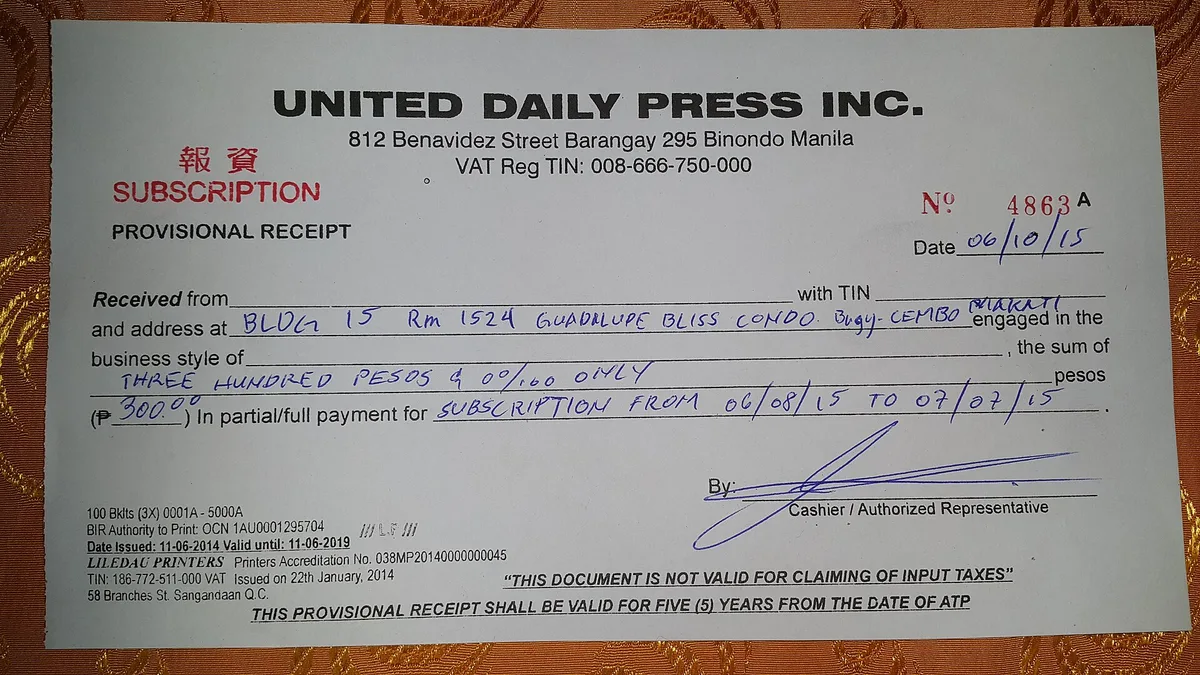
- Attach the evidence: receipts, emails, photos, delivery records, and a short timeline of what happened.
- For billing errors on a credit card, follow up in writing to the billing inquiries address, so your rights under the law are preserved.
- Track deadlines. Sixty days from the statement is the window for covered billing errors.
Mistakes That Sink Good Disputes
Banks assign a reason code to every chargeback, and the codes fall into broad families: technical problems, clerical errors, and issues with the quality of goods or services. Your claim should match the right family and say so clearly. Vague stories lose; specific, documented ones win.
Two habits cause the most damage. Waiting past the deadline is the first. Exaggerating a claim is the second, because issuers can spot inconsistencies, and credibility is the whole game.
Conclusion: Calm, Documented, and On Time
Disputing a charge is not a fight; it is a process. The banks built it for exactly the situations that feel unfair, and the laws behind it give cardholders real leverage. Contact the merchant, document everything, file with your issuer promptly, and put the key dispute in writing within the window the law sets. Do that, and the odds tilt firmly your way.