A cross-border payment is money moving from a bank account in one country to an account in another. Domestic transfers ride one national rail. International transfers often ride several, stitched together by intermediary banks. Each stitch adds time, cost and a place where something can go wrong.
The core answer is this: cross-border payments are slow because no single settlement system spans both countries. Your bank must find a bank in the destination country that will accept the deposit, and that bank may need another intermediary of its own. Every hop is a separate message, a separate fee and a separate window for a manual check. Merriam-Webster defines the verb "cross" simply as to go from one side of to the other — but in payments, that crossing runs through a chain of institutions, not a bridge.
This piece walks the chain step by step: how correspondent banking works, where the fees actually sit, how foreign-exchange spreads add a second hidden charge, and what the newer instant-payment rails are changing. The recurring question throughout is the same one worth asking of any payment: where does the fee sit, and who eats it?
How does correspondent banking actually move money?
Correspondent banking is the arrangement that lets a bank serve customers in countries where it has no branches. Bank A in one country holds an account at Bank B in another. When a customer wants to send money abroad, Bank A does not physically ship cash. It debits the customer and credits its own account at Bank B, which then credits the recipient's bank.
That works cleanly when the two banks have a direct relationship. It often does not. A small regional bank may have no correspondent in the destination country at all. The payment then passes through two or three intermediaries, each holding accounts at the next. Messaging between them historically ran on standardized interbank message formats — the plumbing most people shorthand as SWIFT, though the messages and the settlement are separate things. A message says "move the money"; the actual settlement happens later, between account balances held at each link in the chain.
Each hop is a checkpoint. Compliance teams screen the payment for sanctions and suspicious patterns. Time zones mean a payment initiated in the afternoon may not be processed until the next business day somewhere else. A mismatched beneficiary name can freeze the whole chain until a human fixes it. None of these steps is individually slow. Stacked together, they turn seconds of processing into days of elapsed time.
Where do the fees stack up?
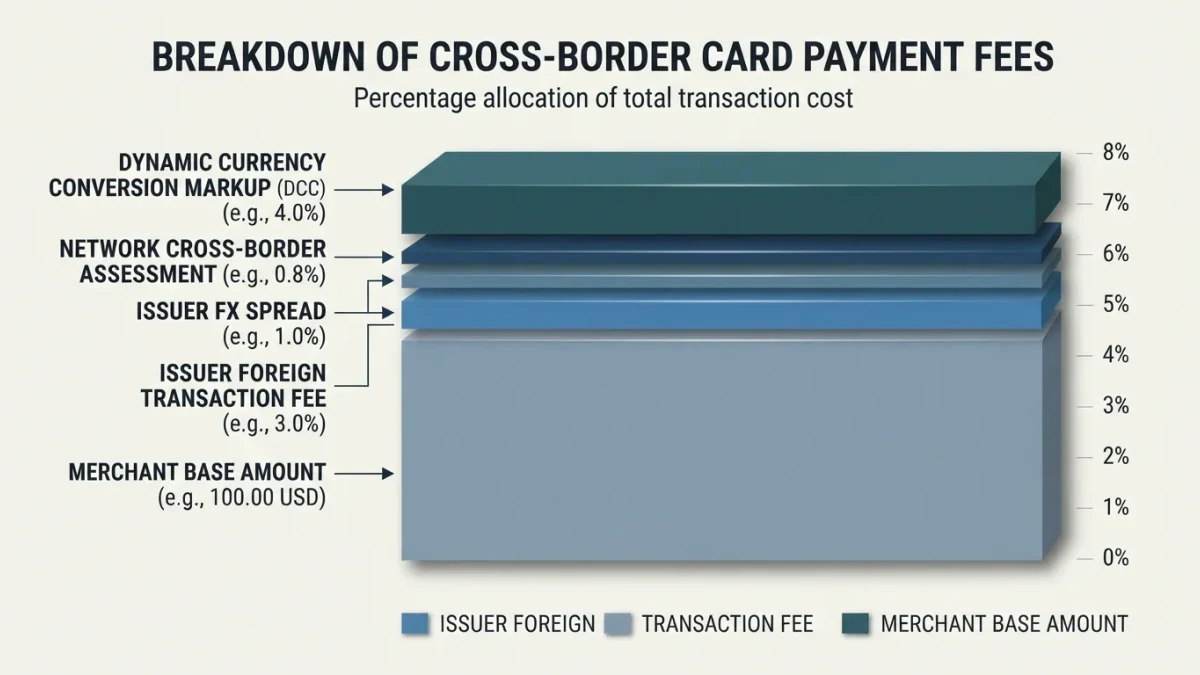
Cross-border fees rarely appear as one line item. They accumulate in layers, and the sender usually sees only the top layer.
- Wire transfer fees. The sending bank charges an upfront fee for initiating an international transfer. Receiving banks often charge their own incoming-wire fee, which the sender may never see — it is simply deducted from the amount that arrives.
- Intermediary bank fees. Every correspondent in the chain can take a cut for passing the payment along. These are deducted from the principal, which is why the received amount sometimes lands short of what was sent even when the sender paid a flat fee.
- FX conversion. If the payment changes currency, the spread on that conversion is usually the largest single cost. More on that below.
The structure matters more than any single number. A flat wire fee is visible and negotiable. Intermediary deductions are invisible until the recipient checks the deposit. The FX spread is invisible unless the sender knows the mid-market rate — the midpoint between what buyers bid and sellers ask on the open market — and compares. This layered opacity is the defining feature of the correspondent model: the party choosing the route is rarely the party paying for it.
Domestic readers will recognize the pattern from other rails. On cards, the question of where a fee sits and who ultimately pays it has its own long answer, which we covered in What Interchange Fees Actually Are — and Who Ends Up Paying Them. Cross-border correspondent fees behave the same way economically: they are real costs that someone downstream absorbs.
How does the FX spread hide in the exchange rate?
When a payment converts currencies, the bank applies its own rate rather than the mid-market rate. The difference between the two is the spread, quoted as a percentage of the amount converted. It is not listed as a fee. It is simply a worse rate than the one you could find published on any currency market source.
Two payments of the same size can cost radically different amounts depending on who converts the currency and when. A payment converted by the sending bank at that bank's rate may carry a wider spread than the same payment converted by a specialized provider. A payment routed through an intermediary that converts mid-chain may pick up a conversion the sender never asked for.
We go deeper on the mechanics in Where the FX Markup Hides in Cross-Border Payments. The practical takeaway for any sender: ask for the full rate applied, compare it to the mid-market rate, and ask whether any intermediary in the chain will convert currency on the way through.
What is changing — and why now?
Three forces are eroding the friction, none of them instant.
First, domestic instant-payment rails keep expanding, and several countries have linked or are building links between them. When two national instant systems connect directly, a payment can move end to end in seconds, because the settlement happens on each country's own fast rail rather than through a correspondent chain. Coverage is uneven: the countries with mature instant rails are ahead of the rest, and a linked pair of rails does not help a payment going somewhere else.
Second, non-bank providers have built multi-currency networks that hold balances in many countries at once. Instead of moving money across borders for every transaction, these providers net payments locally: money in, money out, settled within each country, with only the net difference actually crossing a border. This is the same netting logic that makes card networks work, applied to bank transfers.
Third, regulators have pushed on the problem directly. Standard-setting bodies for payments have published frameworks aimed at making cross-border payments faster, cheaper and more transparent, and national regulators have pressed banks on fee disclosure. Disclosure does not lower a fee by itself, but it makes the spread visible enough to shop against.
None of this retires correspondent banking. For payments between countries without linked rails, or in currencies with thin provider coverage, the chain remains the only route. The change is that the chain is no longer the only option for the highest-volume corridors.
What this means for businesses and senders
Our analysis of the current state: the speed problem and the cost problem have the same root — route opacity — so the practical fixes are about visibility first, rails second.
- Ask the sending bank for a full breakdown: wire fee, expected intermediary deductions, and the exact FX rate applied against mid-market.
- For recurring cross-border payments, compare the total landed cost across providers, not the advertised fee. A zero-fee transfer with a wide spread can cost more than a fee-charging one at mid-market.
- For businesses paying suppliers abroad, check whether the supplier can accept payment in a currency you can hold, which moves the conversion decision to the party better positioned to make it.
Domestic infrastructure offers a useful benchmark for what "fixed" looks like. The United States' ACH network explains a lot about why even domestic bank transfers settle on a delay, which we covered in How ACH Transfers Move Money Between Banks and Why Settlement Waits — and cross-border chains stack several of those settlement waits end to end. We covered a connected angle in How ACH Transfers Move Money Between Banks and Why Settlement Waits.
What remains unresolved
The evidence here establishes the mechanism: correspondent chains add hops, hops add cost and delay, and FX spreads add a charge that fee disclosures alone do not surface. What the newer rails have not yet settled is reach. Instant links and netting networks concentrate in high-volume corridors. The long tail of currency pairs and smaller countries still runs through the old chain, and there is no announced timetable under which that changes. Until coverage widens, the practical defense for any sender is the same as it has always been: know the route, and ask where each fee sits.